Place Order
Initialization
All examples on this page assume the following initialization has been completed:
from tigeropen.trade.trade_client import TradeClient
from tigeropen.tiger_open_config import TigerOpenClientConfig

client_config = TigerOpenClientConfig(props_path='your_config_directory_path')
trade_client = TradeClient(client_config)
For details, see Prerequisites.
Place Order
TradeClient.place_order():
Description
Places a trading order. The sections below explain supported instruments, order types, sides, quantities, and related parameters.
Before running the program, review User and Account Types and Order and Trading Rules. Confirm that the account supports the order type and that the instrument can be traded at the intended time. If placement fails, see Error Codes.
After place_order accepts the order, it populates order.id, which you can use for queries or cancellation. An order ID confirms submission, not execution. Execution is asynchronous, and the order may later be filled or rejected. Check its status with get_order or get_orders before taking further action.
NOTE
- Market orders (MKT) and stop orders (STP) do not support pre-market and after-hours trading. Set
outside_rth=Falsewhen placing these orders.- For shortable instruments, position locking is currently not supported, so you cannot simultaneously hold long and short positions in the same instrument
- For attached orders, the primary order type currently supports only limit orders
- Market orders (MKT) and paper trading accounts do not support
time_in_force='GTC'.- Paper trading accounts do not currently support orders for warrants and callable bull/bear contracts
Order Status Description
-
How to determine partial fill status for prime and paper trading accounts?
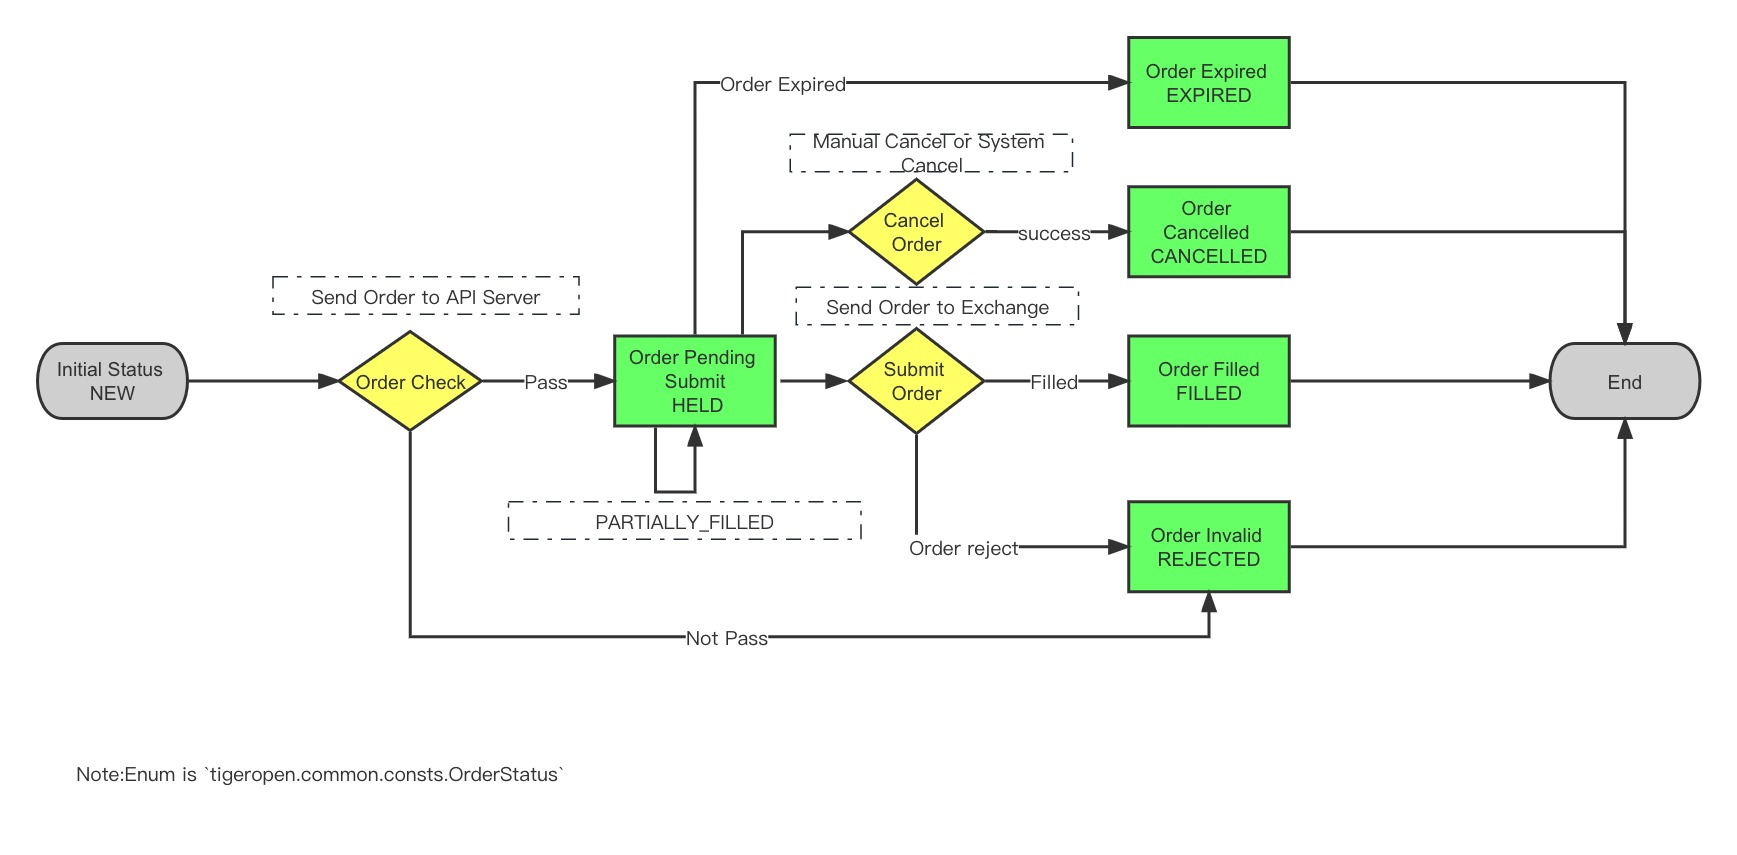
An order whose status is not FILLED, including NEW, CANCELLED, EXPIRED, or REJECTED, may still be partially filled. Check whether
filledis greater than 0. -
How to determine partial fill status for global accounts?
Order status is FILLED and the filled quantity is greater than 0
Order Status Flow:
Other Notes
- For certain U.S. index options (e.g., SPXW) and ETF options such as IWM/SPY/QQQ, contracts with expirations throughout the week (Monday to Friday) are supported for trading. The actual available expirations are subject to exchange listings.
- Direct opening of reverse positions is prohibited. For example, when currently holding 100 long shares, directly selling 200 shares (intending to establish a net short position of 100 shares) will be rejected. You must first close the existing 100 long shares, then perform a new sell operation.
Parameters
Order object (tigeropen.trade.domain.order.Order)
You can use utility functions from tigeropen.common.util.order_utils, such as limit_order(), market_order(), to generate order objects locally based on your specific order type and parameter requirements. For creation methods, see the Order Object - Construction Methods section, or use TradeClient.create_order() to request an order number from the server and then generate the order object (not recommended).
Parameters
| Parameter | Type | Description | Market Order | Limit Order | Stop Order | Stop-Limit Order | Trailing Stop Order |
|---|---|---|---|---|---|---|---|
| account | str | User authorized account: 402901 | Required | Required | Required | Required | Required |
| order_id | int | Order number, used to prevent duplicate orders. Can be obtained through the order ID API. If 0 is passed, the server will automatically generate an order number. When passing 0, duplicate order prevention is not possible, please choose carefully | Optional | Optional | Optional | Optional | Optional |
| symbol | str | Stock symbol e.g.: AAPL; (For warrants/callable bull bear contracts when sec_type, use the 5-digit number below the name in the app warrant/bull bear contract list) | Required | Required | Required | Required | Required |
| sec_type | str | Contract type (STK Stock, OPT US Stock Options, WAR HK Warrants, IOPT HK Callable Bull/Bear Contracts, FUT Futures, CC Crypto) | Required | Required | Required | Required | Required |
| action | str | Trading direction BUY/SELL | Required | Required | Required | Required | Required |
| order_type | str | Order type. MKT (Market Order), LMT (Limit Order), STP (Stop Order), STP_LMT (Stop-Limit Order), TRAIL (Trailing Stop Order) | MKT | LMT | STP | STP_LMT | TRAIL |
| quantity | int | Order quantity (HK stocks, Shanghai-Hong Kong Stock Connect, warrants, callable bull/bear contracts have minimum quantity restrictions) | Required | Required | Required | Required | Required |
| quantity_scale | int | Order quantity offset, defaults to 0. For fractional shares, quantity and quantity_scale combine to represent the actual order quantity. E.g., quantity=111, quantity_scale=2, then actual quantity=111*10^(-2)=1.11 | Not Required | Not Required | Not Required | Not Required | Not Required |
| total_cash_amount | float | Total order amount, only needed for dollar-based orders. Not needed for quantity-based orders | Not Required | Not Required | Not Required | Not Required | Not Required |
| limit_price | float | Limit price, required when order_type is LMT or STP_LMT | Not Required | Required | Not Required | Required | Not Required |
| aux_price | float | Stock order stop trigger price. Meaning is price difference. When both trailing_percent exist, overridden by trailing_percent. Required when order_type is STP or STP_LMT. When order_type is TRAIL, this is the trailing amount | Not Required | Not Required | Required | Required | Optional |
| trailing_percent | float | Trailing stop order - stop percentage. When order_type is TRAIL, aux_price and trailing_percent are mutually exclusive, with trailing_percent taking priority | Not Required | Not Required | Not Required | Not Required | Optional |
| outside_rth | bool | true: Allow pre-market and after-hours trading (US stocks only), false: Don't allow, defaults to allow. (Market orders, stop orders, trailing stop orders are only valid during market hours and will ignore the outside_rth parameter) | Not Required | Optional | Optional | Not Required | Optional |
| trading_session_type | TradingSessionType | US stock order session (limit orders only). Enum values see:trading-session | Not Required | Optional | Not Required | Optional | Not Required |
| adjust_limit | float | Price micro-adjustment range (default 0 means no adjustment, positive for upward adjustment, negative for downward adjustment), automatically adjusts the input price to a valid price level. E.g., 0.001 means upward adjustment not exceeding 0.1%; -0.001 means downward adjustment not exceeding 0.1%. Default 0 means no adjustment | Not Required | Optional | Optional | Optional | Optional |
| market | str | Market (US stocks: US, HK stocks: HK, Shanghai-Hong Kong Stock Connect: CN) | Optional | Optional | Optional | Optional | Optional |
| currency | str | Currency (US stocks: USD, HK stocks: HKD, Shanghai-Hong Kong Stock Connect: CNH) | Optional | Optional | Optional | Optional | Optional |
| time_in_force | str | Order validity period, can only be DAY (valid for the day), GTC (valid until canceled, maximum validity 180 days), GTD (valid until specified time), defaults to DAY | Optional | Optional | Optional | Optional | Optional |
| expire_time | int | Order validity end time, 13-digit timestamp in milliseconds (required when time_in_force is GTD, invalid for other types) | Not Required | Optional | Optional | Not Required | Optional |
| exchange | str | Exchange (US stocks: SMART, HK stocks: SEHK, Shanghai-Hong Kong Stock Connect: SEHKNTL, Shenzhen-Hong Kong Stock Connect: SEHKSZSE) | Optional | Optional | Optional | Optional | Optional |
| expiry | str | Expiration date (options, warrants, callable bull/bear contracts only) | Optional | Optional | Optional | Optional | Optional |
| strike | str | Strike price (options, warrants, callable bull/bear contracts only) | Optional | Optional | Optional | Optional | Optional |
| right | str | Option direction PUT/CALL (options, warrants, callable bull/bear contracts only) | Optional | Optional | Optional | Optional | Optional |
| multiplier | float | Multiplier, quantity per lot (options, warrants, callable bull/bear contracts only) | Optional | Optional | Optional | Optional | Optional |
| local_symbol | str | For warrants/callable bull bear contracts, this field is required - the 5-digit number below the name in the app warrant/bull bear contract list | Optional | Optional | Optional | Optional | Optional |
| secret_key | str | Trader key, for institutional users only | Optional | Optional | Optional | Optional | Optional |
| user_mark | str | Order note information, cannot be modified after placing order, returns userMark information when querying orders | Optional | Optional | Optional | Optional | Optional |
-
Attached Order Parameters
Attached Orders are orders that can achieve take-profit or stop-loss effects on the main order through attached sub-orders. The attachable sub-order types are limit orders (for take-profit) and stop-limit/stop orders (for stop-loss). Attached orders can be implemented by adding the following parameters
Parameter Type Description Attached Stop Loss Attached Take Profit Limit/Stop/Stop-Limit (One-Cancels-All only) leg_type str Attached order type. 'PROFIT' for take-profit order type, 'LOSS' for stop-loss order type Required Required Required price float Attached order price Required Required Required time_in_force str Attached order validity period. 'DAY' (valid for the day) and 'GTC' (valid until canceled - Good-Til-Canceled) Optional Optional Optional outside_rth bool Whether attached order allows pre-market and after-hours trading (US stocks only). True allows, False doesn't allow Optional Optional Optional limit_price float Limit order price Not Required Not Required LMT and STP_LMT Required trailing_percent float Trailing stop order - stop percentage. When using trailing stop orders, you must fill in either stop loss percentage (stopLossTrailingPercent) or stop loss amount (stopLossTrailingAmount). If both are filled, the stop loss percentage takes priority Optional Not Required Not Required trailing_amount float Trailing stop order - stop amount. When using trailing stop orders, you must fill in either stop loss percentage (stopLossTrailingPercent) or stop loss amount (stopLossTrailingAmount). If both are filled, the stop loss percentage takes priority Optional Not Required Not Required quantity int Order quantity Required Required Required
- TWAP/VWAP Order Parameters
TWAP supports stocks and options; VWAP supports stocks only. Both are valid only during regular market hours and do not support pre-market order placement.
| Parameter | Type | Algorithm Parameter | Description | TWAP | VWAP |
|---|---|---|---|---|---|
| order_type | str | Order type, TWAP/VWAP | Required | Required | |
| account | str | Trading account | Required | Required | |
| symbol | str | Stock symbol e.g.: AAPL | Required | Required | |
| sec_type | str | TWAP supports STK and OPT; VWAP supports STK only | Required | Required | |
| total_quantity | int | Order quantity | Required | Required | |
| algo_params | AlgoParams | Algorithm parameters, generated via tigeropen.common.util.order_utils.algo_order_params | Optional | Optional | |
| - | int | start_time | Strategy start time (13-digit millisecond timestamp) | Optional | Optional |
| - | int | end_time | Strategy end time (13-digit millisecond timestamp) | Optional | Optional |
| - | float | participation_rate | Maximum participation rate (maximum proportion of daily average volume, 0.01-0.5) | Not applicable | Optional |
-
Iceberg Order Parameters
Iceberg orders only support US stock underlying assets (sec_type=STK), can only be placed during market hours, and do not support pre-market orders. Iceberg orders split large orders into smaller batches, exposing only
display_sizequantity to the market at a time to reduce market impact.Parameter Type Description Required order_type str Order type, fixed as ICEBERGRequired account str Trading account Required symbol str Stock symbol, e.g. AAPL Required sec_type str Contract type, supports only STK Required action str Trade direction BUY/SELL Required quantity int Total order quantity Required limit_price float Limit price, required when price_type is LIMIT_PRICE Conditional display_size int Display quantity per slice (visible to market) Optional min_display_size int Minimum display quantity (actual display randomized between [min_display_size, display_size]), must be ≤ display_size Optional check_intervals int Price check interval (seconds) Optional price_type str Price type: LIMIT_PRICE/ASK_PRICE/BID_PRICE/LATEST_PRICE, default LIMIT_PRICEOptional start_time int Strategy effective start time (13-digit millisecond timestamp) Optional end_time int Strategy effective end time (13-digit millisecond timestamp) Optional
Return
Returns order ID if successful, throws exception if failed.
If order is placed successfully, the Order object's id will be populated with the actual order number.
Rate Limit
The base rate limit is 120 requests/minute.
Contract Object Examples
from tigeropen.common.util.contract_utils import stock_contract, option_contract, option_contract_by_symbol, \
    future_contract, war_contract_by_symbol, iopt_contract_by_symbol, cc_contract

# US stocks
contract = stock_contract(symbol='TIGR', currency='USD')

# Hong Kong stocks
contract = stock_contract(symbol='00700', currency='HKD')

# Options
contract = option_contract(identifier='AAPL  190118P00160000')
contract = option_contract_by_symbol('JD', expiry='20211015', strike=45.0, put_call='PUT', currency='USD')

# Futures
# Prime/Paper Trading
from tigeropen.common.util.contract_utils import future_contract
contract = future_contract(symbol='CL2312', currency='USD')
# Global
from tigeropen.common.util.contract_utils import future_contract
contract = future_contract(symbol='CL', currency='USD', expiry='20190328', multiplier=1.0, exchange='SGX')

# Hong Kong warrants
contract = war_contract_by_symbol('01810', '20221116', 14.52, 'CALL', local_symbol='14759', multiplier=2000,
                                  currency='HKD')
# Hong Kong CBBCs
contract = iopt_contract_by_symbol('02318', '20200420', 87.4, 'CALL', local_symbol='63379', currency='HKD')

# Cryptocurrency
contract = cc_contract('BTC')
Limit Order (LMT)
from tigeropen.common.util.contract_utils import option_contract, stock_contract
from tigeropen.common.util.order_utils import limit_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=0.1, quantity=1)

# Place order
oid = trade_client.place_order(order)

print(order)
# >>> Order({'account': '111111', 'id': 2498911111111111111, 'order_id': None, 'parent_id': None, 'order_time': None, 'reason': None, 'trade_time': None, 'action': 'BUY', 'quantity': 1, 'filled': 0, 'avg_fill_price': 0, 'commission': None, 'realized_pnl': None, 'trail_stop_price': None, 'limit_price': 0.1, 'aux_price': None, 'trailing_percent': None, 'percent_offset': None, 'order_type': 'LMT', 'time_in_force': None, 'outside_rth': None, 'order_legs': None, 'algo_params': None, 'secret_key': None, 'contract': AAPL/STK/USD, 'status': 'NEW', 'remaining': 1})
print(order.status)  # Order status
print(order.reason)  # If order fails, reason contains the failure reason

# If order is successful, order.id contains the order ID, which can be used for querying or canceling the order
my_order = trade_client.get_order(id=order.id)
oid = trade_client.cancel_order(id=order.id)
# Or modify the order object
trade_client.modify_order(order, limit_price=190.5)
Market Order (MKT)
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import market_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = market_order(account=client_config.account, contract=contract, action='BUY', quantity=1)

# Place order
oid = trade_client.place_order(order)
Market Order by Amount (MKT)
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import market_order_by_amount
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = market_order_by_amount(account=client_config.account, contract=contract, action='BUY', amount=100)

# Place order
oid = trade_client.place_order(order)
Stop Order (STP)
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import stop_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = stop_order(account=client_config.account, contract=contract, action='SELL', aux_price=1, quantity=1)

# Place order
oid = trade_client.place_order(order)
Stop Limit Order (STP_LMT)
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import stop_limit_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = stop_limit_order(account=client_config.account, contract=contract, action='SELL', limit_price=200.0, aux_price=180.0, quantity=1)

# Place order
oid = trade_client.place_order(order)
Trailing Stop Order (TRAIL)
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import trail_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = trail_order(account=client_config.account, contract=contract, action='SELL', quantity=1, trailing_percent=8.0, )

# Place order
oid = trade_client.place_order(order)
Attached Orders
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import limit_order, limit_order_with_legs, order_leg, algo_order_params, \
    algo_order
# Limit order + attached orders (only limit orders support attached orders)
stop_loss_order_leg = order_leg('LOSS', 8.0, time_in_force='GTC',outside_rth=False)  # Attached stop loss
stop_loss_order_leg1 = order_leg('LOSS', 8.0, limit_price=7.5,outside_rth=False)  # Attached stop loss limit order
stop_loss_order_leg2 = order_leg('LOSS', 8.0, trailing_percent=0.8,outside_rth=False)  # Attached trailing stop (by percentage)
stop_loss_order_leg3 = order_leg('LOSS', 8.0, trailing_amount=2.0,outside_rth=False)  # Attached trailing stop (by amount)

profit_taker_order_leg = order_leg('PROFIT', 12.0, time_in_force='GTC',outside_rth=False)  # Attached take profit
main_order = limit_order_with_legs(account, contract, 'BUY', 100, limit_price=10.0,
order_legs=[profit_taker_order_leg, stop_loss_order_leg])
oid = trade_client.place_order(main_order)
# Query attached orders associated with the main order
order_legs = trade_client.get_open_orders(account, parent_id=main_order.id)
print(order_legs)
Main Order + Attached Stop Loss Order
Attached stop loss orders can be market orders, limit orders, or trailing stop orders
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import limit_order, limit_order_with_legs, order_leg, algo_order_params, \
    algo_order
# Limit order + attached orders (only limit orders support attached orders)
stop_loss_order_leg = order_leg('LOSS', 8.0, time_in_force='GTC',outside_rth=False)  # Attached stop loss market order
stop_loss_order_leg1 = order_leg('LOSS', 8.0, limit_price=7.5,outside_rth=False)  # Attached stop loss limit order
stop_loss_order_leg2 = order_leg('LOSS', 8.0, trailing_percent=0.8,outside_rth=False)  # Attached trailing stop (by percentage)
stop_loss_order_leg3 = order_leg('LOSS', 8.0, trailing_amount=2.0,outside_rth=False)  # Attached trailing stop (by amount)

main_order = limit_order_with_legs(account, contract, 'BUY', 100, limit_price=10.0,
order_legs=[stop_loss_order_leg])
oid = trade_client.place_order(main_order)
# Query attached orders associated with the main order
order_legs = trade_client.get_open_orders(account, parent_id=main_order.id)
print(order_legs)
Main Order + Attached Take Profit Order
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import limit_order, limit_order_with_legs, order_leg, algo_order_params, \
    algo_order
# Limit order + attached orders (only limit orders support attached orders)
profit_taker_order_leg = order_leg('PROFIT', 12.0, time_in_force='GTC',outside_rth=False)  # Attached take profit
main_order = limit_order_with_legs(account, contract, 'BUY', 100, limit_price=10.0,
order_legs=[profit_taker_order_leg])
oid = trade_client.place_order(main_order)
# Query attached orders associated with the main order
order_legs = trade_client.get_open_orders(account, parent_id=main_order.id)
print(order_legs)
Main Order + Attached Bracket Order
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import limit_order, limit_order_with_legs, order_leg, algo_order_params, \
    algo_order
# Limit order + attached orders (only limit orders support attached orders)
stop_loss_order_leg = order_leg('LOSS', 8.0, time_in_force='GTC',outside_rth=False)  # Attached stop loss
profit_taker_order_leg = order_leg('PROFIT', 12.0, time_in_force='GTC',outside_rth=False)  # Attached take profit
main_order = limit_order_with_legs(account, contract, 'BUY', 100, limit_price=10.0,
order_legs=[profit_taker_order_leg, stop_loss_order_leg])
oid = trade_client.place_order(main_order)
# Query attached orders associated with the main order
order_legs = trade_client.get_open_orders(account, parent_id=main_order.id)
print(order_legs)
OCA Orders
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import order_leg, oca_order
contract = stock_contract(symbol='BILI', currency=Currency.USD)
# stop_loss_order_leg = order_leg('STP', price=8.0)
stop_loss_order_leg = order_leg('STP_LMT', price=8.0, limit_price=7.5,outside_rth=False)
profit_taker_order_leg = order_leg('LMT', limit_price=30.0,outside_rth=False)
my_oca_order = oca_order(client_config.account, contract, 'BUY',
                                   order_legs=[stop_loss_order_leg, profit_taker_order_leg],
                                   quantity=1000)
trade_client.place_order(my_oca_order)
Algorithmic Orders
from time import time

from tigeropen.common.util.contract_utils import option_contract, stock_contract
from tigeropen.common.util.order_utils import limit_order, limit_order_with_legs, order_leg, algo_order_params, \
    algo_order
# Algorithmic orders
contract = stock_contract(symbol='AAPL', currency='USD')
# TWAP does not support the participation_rate parameter
# Stock VWAP order
start_time = int(time() * 1000) + 60_000
end_time = start_time + 30 * 60_000
params = algo_order_params(start_time=start_time, end_time=end_time, participation_rate=0.1)
order = algo_order(client_config.account, contract, 'BUY', 1000, 'VWAP', algo_params=params, limit_price=100.0)
oid = trade_client.place_order(order)

# Option TWAP order
contract = option_contract(identifier='AAPL  300118C00200000')
start_time = int(time() * 1000) + 60_000
end_time = start_time + 30 * 60_000
params = algo_order_params(start_time=start_time, end_time=end_time)
order = algo_order(client_config.account, contract, 'BUY', 2, 'TWAP', algo_params=params, limit_price=1.5)
oid = trade_client.place_order(order)
Iceberg Order
Supports only US stocks during market hours. Pre-market orders are not supported. The order can be modified or canceled.
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import iceberg_order
from tigeropen.common.consts import PriceType

contract = stock_contract(symbol='AAPL', currency='USD')

# Iceberg order (basic parameters, limit price mode)
order = iceberg_order(
    account=client_config.account,
    contract=contract,
    action='BUY',
    quantity=1000,
    limit_price=180.0,
    display_size=100
)
trade_client.place_order(order)

# Iceberg order (full parameters)
order = iceberg_order(
    account=client_config.account,
    contract=contract,
    action='BUY',
    quantity=1000,
    limit_price=180.0,
    display_size=100,
    min_display_size=50,
    check_intervals=30,
    price_type=PriceType.LIMIT_PRICE,
    start_time=1750412400000,   # strategy effective start time
    end_time=1750435600000      # strategy effective end time
)
trade_client.place_order(order)
Auction Orders
auction_limit_order Auction Limit Order
auction_market_order Auction Market Order
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import auction_limit_order, auction_market_order
# Generate stock contract
contract = stock_contract(symbol='01810', currency='HKD')
# With OPG, an unfilled opening-auction order is canceled after the auction. DAY participates in the closing auction.
order = auction_limit_order(account=client_config.account, contract=contract, action='BUY', quantity=200,
                            limit_price='10', time_in_force='OPG')
# Auction market order
# order = auction_market_order(account=client_config.account, contract=contract, action='BUY', quantity=200, time_in_force='OPG')

# Place order
oid = trade_client.place_order(order)
Extended/Full Session Orders
Supports only US stocks.
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.consts import TradingSessionType
from tigeropen.common.util.order_utils import limit_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=120, quantity=1)

# Extended hours trading
# order.trading_session_type = TradingSessionType.OVERNIGHT

# Pre-market, regular, and after-hours trading
# order.trading_session_type = TradingSessionType.PRE_RTH_POST

# Full session trading
order.trading_session_type = TradingSessionType.FULL

# Place order
trade_client.place_order(order)
my_order = trade_client.get_order(id=order.id)
print(my_order.user_mark)
Other Examples
Placing Hong Kong Stock Orders
In Hong Kong stock trading, the order quantity must be an integer multiple of the stock's "lot size". Taking Tencent Holdings (00700) as an example, its lot size is 100 shares, so acceptable order quantities are 100, 200, 500, etc. (i.e., multiples of 100).
You can use QuoteClient.get_trade_metas in advance to get the stock's lot size to ensure the order quantity complies with the rules.
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import limit_order
symbol = '00700'

# Get lot size
metas = quote_client.get_trade_metas([symbol])
lot_size = int(metas['lot_size'].iloc[0])

# Generate stock contract
contract = stock_contract(symbol=symbol, currency='HKD')
# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=400.0, quantity=2 * lot_size)
# Place order
oid = trade_client.place_order(order)
Placing Futures Orders
from tigeropen.common.util.contract_utils import future_contract
from tigeropen.common.util.order_utils import limit_order
# Generate futures contract
contract = future_contract(symbol='CL', currency='USD')
# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=0.1, quantity=1)
# Place order
oid = trade_client.place_order(order)
Placing Options Orders
from tigeropen.common.util.contract_utils import option_contract, option_contract_by_symbol
from tigeropen.common.util.order_utils import limit_order
# Generate options contract
contract = option_contract(identifier='AAPL  190118P00160000')
# Or
contract = option_contract_by_symbol('AAPL', '20200110', strike=280.0, put_call='PUT', currency='USD')

# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=0.1, quantity=1)
# Place order
oid = trade_client.place_order(order)
Placing Option Combo Orders
Use a positive limit_price for a net-debit combination and a negative limit_price for a net-credit combination.
from tigeropen.common.consts import ComboType
from tigeropen.common.util.contract_utils import option_contract, option_contract_by_symbol
from tigeropen.common.util.order_utils import combo_order, contract_leg
contract_leg1 = contract_leg(symbol='TSLA', sec_type='OPT', expiry='20230616', strike=220, put_call='CALL',
                            action='BUY', ratio=1)
contract_leg2 = contract_leg(symbol='TSLA', sec_type='OPT', expiry='20230616', strike=225, put_call='CALL',
                            action='SELL', ratio=1)

order = combo_order(client_config.account, [contract_leg1, contract_leg2], combo_type=ComboType.VERTICAL,
                    action='BUY', quantity=1, order_type='LMT', limit_price=1.0)
res = trade_client.place_order(order)
print(res)

# Stock plus option combination
contract_leg1 = contract_leg(symbol='00700', sec_type='STK', action='BUY', ratio=100)
contract_leg2 = contract_leg(symbol='TCH.HK', sec_type='OPT', expiry='20300628', strike=510,
                             put_call='CALL', action='SELL', ratio=1)
order = combo_order(client_config.account, [contract_leg1, contract_leg2], combo_type=ComboType.CUSTOM,
                    action='SELL', quantity=1, order_type='LMT', limit_price=-0.04)
res = trade_client.place_order(order)
Placing Fund Orders
from tigeropen.common.util.contract_utils import fund_contract
from tigeropen.common.util.order_utils import market_order_by_amount
# Generate fund contract
contract = fund_contract(symbol='000001', currency='USD')
# Generate order object
order = market_order_by_amount(account=client_config.account, contract=contract, action='BUY', amount=100.0)
# Place order
oid = trade_client.place_order(order)
Query Contract and Place Order
from tigeropen.common.util.contract_utils import stock_contract
# Get stock contract (not recommended)
contract = trade_client.get_contract('AAPL', sec_type=SecurityType.STK)
# Get order object (not recommended)
order = trade_client.create_order(account=client_config.account, contract=contract, action='SELL', order_type='LMT', quantity=1, limit_price=200.0)
# Place order
oid = trade_client.place_order(order)
Setting Order Attributes
Examples of using uncommon order attributes, such as user_mark
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.consts import TradingSessionType
from tigeropen.common.util.order_utils import limit_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=0.1, quantity=1)
# Set custom order remark (Global accounts need to contact the platform in advance to enable this feature)
order.user_mark = 'my-custom-remark'

# Set order validity to GTC
# order.time_in_force = 'GTC'

# Extended hours trading
# order.trading_session_type = TradingSessionType.OVERNIGHT

# Full session trading
# order.trading_session_type = TradingSessionType.FULL

# Set order to GTD (good till date, valid until specified date)
#order.time_in_force = 'GTD'
#order.expire_time = 1700496000000 # Must specify expiration time
# If using time string
#from tigeropen.common.util.common_utils import date_str_to_timestamp
#order.expire_time = date_str_to_timestamp('2023-07-01 11:00:00', 'US/Eastern')

# Place order
trade_client.place_order(order)
my_order = trade_client.get_order(id=order.id)
print(my_order.user_mark)
Price Adjustment for Orders
Use the contract's tick rules and PriceUtil to normalize an order price. Tick precision can vary by price level, and the API rejects prices that do not match the applicable tick size.
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.price_util import PriceUtil
from tigeropen.common.consts import SecurityType
# Get stock contract
contract = trade_client.get_contract(symbol='AAPL', sec_type=SecurityType.STK)
limit_price = 150.173

# Check if price matches contract tick specifications
is_price_ok = PriceUtil.match_tick_size(price, contract.tick_sizes)

# Adjust price (if is_up parameter is set to True, price adjusts upward. Default False, price adjusts downward)
# If contract price is between 1~1000 with tick size of 0.01, then 150.173 adjusts to 150.17; upward adjustment would be 150.18
limit_price = PriceUtil.fix_price_by_tick_size(price, contract.tick_sizes)

# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=limit_price, quantity=1)

# Place order
trade_client.place_order(order)
Placing Fractional Share Orders
from tigeropen.common.util.contract_utils import stock_contract
from tigeropen.common.util.order_utils import limit_order
# Generate stock contract
contract = stock_contract(symbol='AAPL', currency='USD')
# Generate order object
order = limit_order(account=client_config.account, contract=contract, action='BUY', limit_price=170, quantity=5)
# quantity_scale set to 1, actual order quantity is 5 * 10^-1 = 0.5 shares; if quantity_scale is set to 2, actual order quantity is 5 * 10^-2 = 0.05 shares
order.quantity_scale = 1

# Place order
oid = trade_client.place_order(order)

print(order)
Request to Create Order
TradeClient.create_order():
Description
Request order ID and create order object (not recommended). It's recommended to use utility functions under tigeropen.common.util.order_utils to create orders locally, such as limit_order, market_order.
Parameters
| Parameter | Type | Description | Market Order | Limit Order | Stop Order | Stop Limit Order | Trailing Stop Order | Auction Limit Order | Auction Market Order |
|---|---|---|---|---|---|---|---|---|---|
| account | str | Account ID, if not provided, returns all associated accounts | Optional | Optional | Optional | Optional | Optional | Optional | Optional |
| contract | Contract | Contract object | Required | Required | Required | Required | Required | Required | Required |
| action | str | Buy/Sell direction, 'BUY': Buy, 'SELL': Sell | Required | Required | Required | Required | Required | Required | Required |
| order_type | str | Order type, 'MKT' Market / 'LMT' Limit / 'STP' Stop / 'STP_LMT' Stop Limit / 'TRAIL' Trailing Stop | MKT | LMT | STP | STP_LMT | TRAIL | AL | AM |
| quantity | int | Order quantity, must be positive integer | Required | Required | Required | Required | Required | Required | Required |
| limit_price | float | Limit order price, required when order type is LMT or STP_LMT or AL | Required | Required | Required | ||||
| aux_price | float | For stop orders: stop price; For trailing stop orders: trail amount | N/A | N/A | Required | Required | Optional | Optional | Optional |
| trail_stop_price | float | Trailing stop order--price that triggers the stop order | N/A | N/A | N/A | N/A | N/A | N/A | N/A |
| trailing_percent | float | Trailing stop order--percentage (at least one of aux_price and trailing_percent must be filled) | N/A | N/A | N/A | N/A | Optional | N/A | N/A |
| adjust_limit | float | Price adjustment range (default 0 means no adjustment, positive for upward, negative for downward), automatically adjusts input price to legal price levels. E.g., 0.001 means upward adjustment within 0.1%; -0.001 means downward adjustment within 0.1%. Default 0 means no adjustment | N/A | Optional | Optional | Optional | Optional | N/A | N/A |
| time_in_force | str | Order validity period, can only be DAY (valid for the day), GTC (valid until canceled, max 180 days), or GTD (valid until specified time). Defaults to DAY. GTD requires the expire_time parameter. | Optional | Optional | Optional | Optional | Optional | Optional (HK auction orders need OPG for the opening auction and DAY for the closing auction) | Optional (HK auction orders need OPG for the opening auction and DAY for the closing auction) |
| outside_rth | bool | True: Allow pre/post market trading (US stocks only), False: Don't allow, default True. (Market orders only valid during market hours, will ignore outside_rth parameter) | N/A | Optional | Optional | N/A | Optional | Required (Fixed as True) | Required (Fixed as True) |
| order_legs | object | Attached order list, see examples above | Optional | Optional | Optional | Optional | Optional | N/A | N/A |
| algo_params | object | Algorithmic order parameters, see examples above | Optional | Optional | Optional | Optional | Optional | N/A | N/A |
| secret_key | str | For institutional users only, trader key | Optional | Optional | Optional | Optional | Optional | Optional | Optional |
| user_mark | str | Order remark information, cannot be modified after placing order, returns userMark info when querying orders (Global accounts need to configure developer personal information) | Optional | Optional | Optional | Optional | Optional | Optional | Optional |
Example
from tigeropen.common.util.contract_utils import stock_contract
contract = stock_contract(symbol='AAPL', currency='USD')
order = openapi_client.create_order(account, contract, 'BUY', 'LMT', 100, limit_price=5.0)

trade_client.place_order(order)
Rate Limit
The base rate limit is 120 requests/minute.
Currency Exchange Order
TradeClient.place_forex_order(seg_type, source_currency, target_currency, source_amount)
Description
Currency exchange order, returns Order object
Parameters
| Parameter | Type | Description |
|---|---|---|
| seg_type | SegmentType | Account segment. Available: SegmentType.SEC for securities; SegmentType.FUT for commodities, can be imported from tigeropen.common.consts.SegmentType |
| source_currency | Currency | Currency to be converted |
| target_currency | Currency | Currency to receive after conversion |
| source_amount | Float | Amount of source currency to be converted |
Example
from tigeropen.common.util.contract_utils import stock_contract
order = trade_client.place_forex_order(seg_type='FUT', source_currency='USD', target_currency='HKD',
                                       source_amount=50)
print(order)
Example Response
Order({'account': '11111', 'id': 30323340487950336, 'order_id': 1447, 'parent_id': None, 'order_time': 1680247928000, 'reason': '', 'trade_time': 1680247928000, 'action': 'SELL', 'quantity': 50, 'filled': 0, 'avg_fill_price': 0.0, 'commission': 0.0, 'realized_pnl': 0.0, 'trail_stop_price': None, 'limit_price': 7.74991, 'aux_price': None, 'trailing_percent': None, 'percent_offset': None, 'order_type': 'LMT', 'time_in_force': 'DAY', 'outside_rth': False, 'order_legs': None, 'algo_params': None, 'algo_strategy': 'LMT', 'secret_key': None, 'liquidation': False, 'discount': 0.0, 'attr_desc': None, 'source': 'OpenApi', 'adjust_limit': None, 'sub_ids': None, 'user_mark': '', 'update_time': 1680247928000, 'expire_time': None, 'can_modify': True, 'contract': USD.HKD/FOREX/HKD, 'status': 'NEW', 'remaining': 50})Updated about 1 month ago